
The Smartest Guys on the Planet: Why Even Very Smart People Can Think Really Dumb Things
Not too long ago, I listened to tech investor Jason Calacanis on a podcast. He confidently made a number of strange assertions, including that Russia’s invasion of Ukraine could easily be resolved with some land swaps and that the U.S. government had no business regulating mergers and acquisitions because it can’t predict the future.
Nobody with deep expertise in Eastern Europe or antitrust law would make either claim so casually, but there he was, confidently asserting simple solutions to complex problems. It reminded me of Bethany McLean’s classic, The Smartest Guys in the Room, which chronicled the incredible rise and disastrous fall of Enron.
The funny thing about Enron is that, at one point, they really were the smartest guys in the room. Early in my career, I worked on a natural gas trading desk and the Enron operation was top notch. Their problem was arrogance, which led them to make big bets on things they barely understood. Clearly, we’re seeing a similar hubris playing out in Silicon Valley today.
When Success Breeds Overconfidence
In Careless People, former Meta executive Sarah Wynn-Williams describes the Silicon Valley executives she worked with as so wealthy and powerful that they had grown out of touch with many of the world’s realities. At one point, during a discussion about how much to charge for internet service for refugees, she describes a senior leader’s surprise with the realization that the inhabitants of refugee camps lack employment.
There are strong echoes of the Enron story. Enron started out as a genuine innovator, revolutionizing energy trading as markets deregulated in the 1990s. The problem was that its success in energy trading led executives to believe they had discovered a universal business model that could be applied to almost anything—from water and broadband to advertising and shipping. It couldn’t.
You can see the same sort of hubris in Calacanis’s comments on Ukraine, which is not something a tech investor really needs to know about. Still, if he wanted to understand how Vladimir Putin himself justified the invasion, he could have read the 6000-word essay the Russian leader published just months beforehand, laying out his historical case for war.
He would find very little about NATO, which is mentioned only twice, and then only in passing. At the same time, the medieval Rus empire, Bohdan Khmelnytsky and Polish–Lithuanian Commonwealth were all mentioned roughly half a dozen times. You would have to know some Eastern European history to understand the significance of those things, but it wouldn’t take much to grasp the fact that the roots of the conflict were laid long before this century began.
Like Enron’s executives, Calacanis seems to think that competence in one area will spill over to another. It rarely does.
The Genius Trap
One of the defining aspects of the Enron story was the “culture of genius” that CEO Jeff Skilling built at the company. It recruited aggressively from Harvard, Stanford, Wharton, and other elite schools. Employees were expected to be exceptional. The company’s identity became inseparable from the belief that it employed the smartest people in business.
That may sound like a recipe for excellence, but in Cultures of Growth, Stanford social psychologist Mary C. Murphy argues that cultures of genius often undermine an organization’s ability to learn. Talent is seen as innate, so the organization’s job is to identify the stars, reward them lavishly, and get out of their way.
Yet cultures of genius often create perverse incentives. If talent is innate, you can never admit a mistake or that you don’t know something. Show any weakness and you risk not being identified as one of the chosen few. You don’t question, explore, or work to learn new things. Geniuses, after all, already know everything. Why bother learning?
Theo Baker described a similar culture ingrained at Stanford in his recent memoir, How To Rule The World. While most students experience the normal humdrum campus life, those chosen few who are able to keep up appearances are deemed high agency and gain access to the “Stanford within Stanford,” replete with mentorships, invites to yacht parties and access to venture capital cash to fund any idea that springs from their young minds.
The idea that exceptional people are exempt from normal constraints is at least as old as Dostoyevsky’s Crime and Punishment, and you can see what makes it so attractive. If you’re a special, “high agency” person like Calacanis, then you aren’t bound by the same rules as mere mortals. So why bother learning about the Zaporizhian Sich or Truce of Andrusovo, much less the legal nuances of the Sherman and Clayton Antitrust Acts?
The Next Big Bet
Artificial Intelligence is perhaps the ultimate “high agency” technology. Much like the trading and risk management techniques that Enron pioneered in the 1990s, it’s highly complex, little understood outside of a small elite and incredibly powerful. Many believe the technology is advancing so quickly that only insiders can really understand what’s happening.
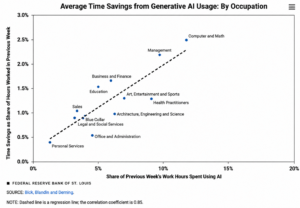
But here too, you can see similar outlines. While people in the tech world are blown away by how the frontier models are impacting their work, it is not at all clear that similar gains will materialize across the rest of the economy. In fact, research from the St. Louis Federal Reserve Bank shows that for most tasks, productivity gains are relatively meager.
Other research seems to bear that out. A recent Duke survey of CFOs found that few see much productivity improvement at all, while another survey of nearly 6,000 senior business executives across the US, UK, Germany, and Australia found that, despite relatively high adoption, nine-in-ten report no impact on employment or productivity in their own firms. According to an analysis published in Harvard Business Review, “AI Workslop” is actually damaging productivity.
That disconnect between investment and realized productivity is beginning to show up in the data. Many enterprises are now trying to cut their AI expenses, while Chinese models are increasingly competitive with frontier models at just a fraction of the cost. At the same time, analysts project AI capital spending to top $1 trillion next year and Carlyle sees a growing capacity trap, with chip producers reluctant to expand production to fully meet demand.
At some point, something has got to give. While it remains to be seen whether tech investors like Jason Calacanis will follow Enron’s path, some of the underlying dynamics certainly seem familiar. If you consider yourself to be truly exceptional, unbound by normal constraints, there is little reason to heed warning signs from others outside your tribe.
Historically, that has proved to be a problem.
Don’t Believe Everything You Think
George Soros made a fortune betting against conventional wisdom. When the British government committed to keeping the pound pegged to the German mark, he bet against it and earned a billion dollars. He later pulled off similar trades against the Thai baht and the Japanese yen. Where others saw a boom, Soros saw a bust right around the corner.
His secret weapon was a theory he calls reflexivity. The basic idea is that expectations don’t form in a vacuum. They are shaped, in part, by our perceptions of what other people believe. The more widely an idea is accepted, the more likely we are to accept it ourselves and that, in turn, reinforces the collective zeitgeist.
What’s interesting about the reflexivity theory is that it doesn’t rely on the merits of the asset in question. You can believe in the transformative power of AI and still recognize that market fundamentals still apply. When we look back at past boom-bust cycles, the problem was never a lack of intelligence or a lack of capital, but a lack of discipline.
The problem is that cultures that celebrate exceptional intelligence eventually begin to mistake intelligence for infallibility. The truth is that smart people are often more easily fooled than most because they expect to see things that others miss. The greatest danger facing elite cultures isn’t a lack of intelligence. It’s the gradual loss of intellectual humility that success can produce.
Nobody, no matter how smart, can afford to believe everything they think.
Greg Satell is Co-Founder of ChangeOS, a transformation & change advisory, a lecturer at Wharton, an international keynote speaker, host of the Changemaker Mindset podcast, bestselling author of Cascades: How to Create a Movement that Drives Transformational Change and Mapping Innovation, as well as over 50 articles in Harvard Business Review. You can learn more about Greg on his website, GregSatell.com, watch his YouTube Channel and connect on LinkedIn.
Like this article? Join thousands of changemakers and sign up to receive weekly insights from Greg’s DigitalTonto newsletter!
Image generated by ChatGPT


